Last updated: September 10, 2026
Key Takeaways
- Use the same principal, such as $15,000 or £25,000, on both offers.
- Compare 36 months with 36 months, 60 with 60, 15 years with 15 years.
- Choosing by APR can go wrong when you expect to walk away after 18 months on a 5-year loan.
- Borrow $10,000 at 8% interest, and the lender is charging 8% per year before most fees, depending on the loan and any required charges.
APR vs interest rate is usually the first head-to-head test when you shop for a loan. Not the only one, though. If you are weighing a mortgage, personal loan, car loan, or refinance offer, a better question is blunt: which one costs less overall for the way you will actually use it? APR generally gets you closer to that answer than interest rate alone.
This piece is for someone looking at loan offers and trying to dodge the classic trap: a lower rate that hides higher fees, or a higher APR that looks ugly on paper but may be tied to a shorter term or a different fee setup. I’m assuming you already have at least two offers in front of you, and you can read the basic terms: interest rate, APR, term length, monthly payment, and fees. This is information, not financial advice; for your own situation, especially with mortgages or business borrowing, a qualified adviser should check the details.
Table of contents
- Which number should you focus on first?
- APR vs interest rate: what each number actually includes
- How I would compare two loan offers step by step
- When does interest rate matter more than APR?
- What makes APR misleading?
- When should you stop relying on APR?
- The mistakes people make when comparing loans
- Which sources should you trust when you compare loans?
Which number should you focus on first?
Start with APR, but only after you check that the loans match on term, amount borrowed, and rate type. APR stands for annual percentage rate; in plain English, it is supposed to show the yearly cost of borrowing more completely than the nominal interest rate.
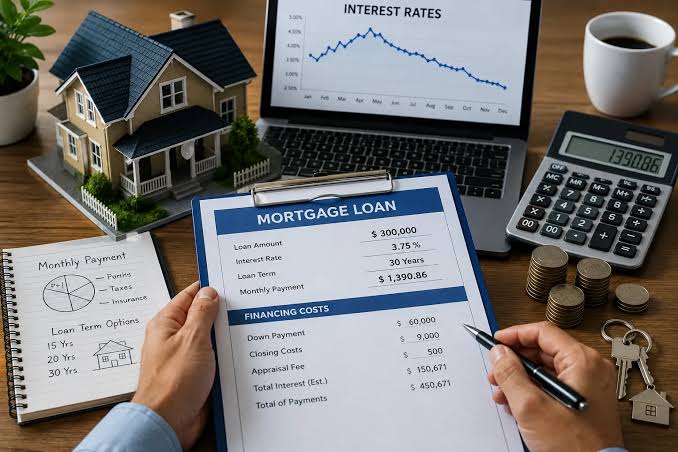
The interest rate is the charge on the principal itself. Say you borrow $10,000 at 8% interest. That means the lender is pricing the use of that money at 8% per year before most fees. APR tries to bundle in some borrowing costs you pay to get the loan, such as certain origination fees, discount points on mortgages, and other finance charges, depending on the loan type and the country’s disclosure rules. Handy, yes. Perfect? No.
The catch is obvious once you’ve seen a few quotes: APR is not a universal scorecard. Disclosure rules vary by country, and even inside one country the calculation can shift by product. In the United States, for example, mortgage APR is governed by disclosure rules under the Truth in Lending Act; for mortgages, the Consumer Financial Protection Bureau explains APR in the Loan Estimate and Closing Disclosure context, and the Federal Trade Commission has plain-language guidance on comparing loan costs. See the CFPB and FTC pages on APR and loan comparison for the general framework. For your own loan, especially if the structure is unusual, it is wise to consult the lender’s disclosures and, if needed, a qualified professional.
I’d use APR as the main sorting tool when the offers are close in structure. I would not treat it as the only tool when the term, payment schedule, or fee timing differs. A loan with a lower APR can still be worse for you if you plan to repay it early and most of the savings in that APR come from upfront fees you will not keep long enough to spread out. Funny how the “cheaper” option can bite later.
APR vs interest rate: what each number actually includes
APR usually includes the interest rate plus certain finance charges; the interest rate does not. That single split is why the numbers often diverge, sometimes by a sliver, sometimes by a mile.
Here is the practical distinction:
- Interest rate: the price of borrowing the principal.
- APR: the annualized cost of borrowing, including the interest rate and some required fees.
If two loans have the same interest rate but one has a $1,500 origination fee and the other has no fee, the APR on the fee-bearing loan should be higher. That’s the whole point of APR: it can expose the cheap-looking rate that is really wrapped around expensive front-end costs.
But APR does not capture everything that affects what you pay. It may exclude late fees, prepayment penalties in some contexts, optional insurance, escrow fluctuations, or costs you choose to add. It also assumes a standard holding period, and that matters a lot. Keep a loan long enough, and a low-rate/high-fee offer can become cheaper. Refinance or pay it off early, and the same offer can turn pricier because you never recovered the upfront cost.
So the “always pick the lowest APR” rule falls apart fast. APR is a better comparison tool, not a complete decision rule. I’d use it as the first filter, then check payment timing, total dollars paid over the planned term, and whether any fee is recoverable if you leave the loan early.
How I would compare two loan offers step by step
Begin with a side-by-side read of the full terms, not just the headline rate. The aim is simple: compare like with like — same amount, same term, same repayment pattern, same currency, and ideally the same type of loan.
- Confirm the loan amount is identical. Use the same principal, such as $15,000 or £25,000, on both offers. Verify the quoted amount is before fees if the lender adds fees to the balance. A problem shows up if one offer quietly finances fees into the loan and the other does not.
- Match the term length exactly. Compare 36 months with 36 months, 60 with 60, 15 years with 15 years. Verify the maturity date or final payment schedule. If one loan is shorter, a lower APR may hide a higher monthly payment that strains cash flow.
- Write down the nominal interest rate. Record the rate as quoted, such as fixed 6.5% or variable at a benchmark plus margin. Verify whether the rate is fixed, adjustable, or introductory. A problem is any offer that starts low and resets later, because the APR may not tell you how painful the reset can be.
- List every required fee. Include origination fees, underwriting fees, application fees, points, document fees, and any mandatory insurance tied to the loan. Verify which fees are required to get the rate. If a fee is optional, don’t force it into the comparison unless you actually plan to pay it.
- Check whether the fees are prepaid or financed. A prepaid fee is paid at closing; a financed fee is added to the balance. Verify how each lender handles it. A problem appears when financed fees increase the principal and therefore the interest you pay on the fee itself.
- Compare APRs only after steps 1 to 5. Put the APRs side by side and see which is lower. Verify the lender’s disclosure document, such as a Loan Estimate, Key Facts Illustration, or equivalent local form. A problem is any APR that looks low but comes with major early repayment restrictions.
- Estimate total dollars paid over your expected holding period. Use the number of months you expect to keep the loan, not the full term if you plan to refinance or sell. Verify the total of payments plus fees. Choosing by APR can go sideways when you know you will exit in 18 months from a 5-year loan.
- Test the payment against your budget. Check the monthly payment and stress it against a higher-rate scenario if the loan is variable. Verify that you can cover it without stretching other essentials. A problem is any “cheap” loan whose monthly payment works only if nothing changes.
Want one plain rule from the whole process? Use APR to compare the price of the loan, but use total repayment and your expected holding period to decide whether that price is actually the one you will pay. A lower APR can still lose if you do not keep the loan long enough to amortize the fees.
When does interest rate matter more than APR?
Interest rate matters more when the fee setup is odd, the loan is short-lived, or the APR calculation gets thrown off by timing. Technical on paper, sure. In real life, it just means the monthly charge sometimes tells you more than the total-year figure.
A lower interest rate can be the better number to watch when:
– the lender’s fees are small or zero,
– you expect to repay early,
– the loan is so short that upfront fees dominate the APR,
– or the APR is based on assumptions that do not match your plan.
A 12-month personal loan is a clean example. If one lender charges a modest fee up front and another does not, the APR may jump because that fee is spread across a short period. But if you only care about the monthly payment and you know you will repay in full within that 12 months, the nominal rate and the fee timing may matter more than the headline APR.
For mortgages, I’d be careful with discount points, which are prepaid interest paid to reduce the rate. The APR may improve or worsen depending on the points structure, but if you sell or refinance before the breakeven point, the lower rate can be a false win. That is math, not magic.
Variable-rate loans need extra attention too. The interest rate may be quoted as “prime + 2%” or “SOFR + margin,” and the APR may reflect only the initial period or a standard calculation. If the rate can change, the path of the rate matters more than a single APR snapshot. Review the adjustment caps, reset frequency, and index used. If those terms are unclear, the APR alone is not enough to compare the deal.
What makes APR misleading?
APR becomes misleading when people treat it like a promise instead of a standard disclosure tool. It is not a forecast of your actual cost in every case, and it can hide differences that matter in real life.
The most common blind spots are:
- Different holding periods. APR assumes a standard way of annualizing cost, but your actual use may be months, not years.
- Different fee timing. A fee paid today hurts more than the same fee spread across payments. APR tries to reflect that, but the real cash flow still matters.
- Different loan structures. Two loans can have the same APR and very different monthly payments because one is shorter.
- Variable rates. APR may not capture future resets in a way that helps you compare risk.
- Prepayment penalties. If you plan to refinance or sell early, a penalty can swamp a small APR advantage.
A generic article often skips the simplest practical test: ask yourself how long you will keep the loan. If the answer is “until the house sells,” “until I refinance,” or “until the car is traded in,” APR is only one piece of the comparison. That is especially true for mortgages and auto loans with add-on products or lender credits.
If you want a broader standard to look at, the U.S. CFPB and the FTC both emphasize reading the full loan estimate, not just the rate box. In the U.K., the Financial Conduct Authority publishes guidance on comparing credit and understanding representative APR. Different regulators use different forms, but the principle is the same: disclosure is there to support comparison, not replace judgment.
When should you stop relying on APR?
Stop relying on APR alone when one of these situations applies, because each one changes the comparison in a material way:
The loans have different terms: a 24-month loan and a 60-month loan are not the same product — compare total repayment and monthly cash flow, not just APR.
You expect to refinance or repay early: upfront fees may never be recovered — calculate your break-even month before judging the offer.
The rate is variable or introductory: the APR may not reflect future resets — read the index, margin, adjustment caps, and reset schedule.
There is a prepayment penalty: the exit cost can erase a lower APR — include that penalty in your comparison if early payoff is realistic.
The lender finances fees into the balance: you pay interest on the fee itself — compare the amount financed, not just the stated APR.
The loans are different types: for example, a personal loan versus a line of credit — APR alone will not capture usage flexibility or draw conditions.
In each case, APR still has value, but it is no longer the main decision number. I’d move to total cost over your expected holding period and the monthly payment you can sustain. If the structure is complex enough that you cannot model it clearly, that is a good point to ask a qualified mortgage broker, loan officer, accountant, or financial adviser to review the documents with you.
The mistakes people make when comparing loans
The worst mistake is comparing the headline rate and ignoring fees. That can make a loan with a low interest rate look cheaper than one with a slightly higher rate and no fees, even when the second loan costs less overall. The fix is to compare APR, then verify what fees are included.
Another common error is comparing loans with different terms as if they were equivalent. A 48-month car loan and a 72-month car loan can have similar payments but very different total interest paid. The fix is to line up term length first, then compare APR.
A third mistake is treating APR as if it predicts the future. It does not. It is a disclosure measure, not a guarantee of what you will pay if you refinance, prepay, or let a variable rate reset. The fix is to model your own holding period and likely exit.
A fourth mistake is ignoring whether a fee is prepaid or rolled into the loan. A financed fee increases the balance and the interest charged on that balance. The fix is to compare cash paid at closing and the amount financed separately.
A fifth mistake is forgetting the budget test. The cheapest loan on paper can still fail if the monthly payment is too high for your actual income and expenses. The fix is to stress the payment, especially if the rate can adjust after 12 months, 24 months, or another set period.
Which sources should you trust when you compare loans?
Trust the lender’s official disclosure forms first, then the regulator’s explanation of how to read them. For U.S. borrowers, the Consumer Financial Protection Bureau’s Loan Estimate and Closing Disclosure guidance is the clearest starting point, and the Federal Trade Commission also explains APR and loan shopping in plain language. For UK borrowers, the Financial Conduct Authority’s consumer credit guidance is useful. For other countries, use your local financial regulator or banking supervisor, because APR rules and fee inclusion differ.
That matters because a true comparison depends on the disclosure standard. Two lenders can both say “APR,” but if the terms, fees, or calculation rules differ, the comparison can be misleading unless you read the official documents side by side.