Last updated: September 10, 2026
Key Takeaways
- Some lenders roll those into the loan balance; others make you pay them at closing.
- If the savings take longer than you will keep the loan, the deal is usually poor.
- The new loan wins for borrowers who can name the reason in one sentence.
- You expect to keep the loan long enough to cross the break-even point.
A refinance calculator answers one blunt question: how long before the savings beat the cost? It also shows whether refinance costs, fees, and the new term fit your situation. I write about consumer finance for a living, and I’m going to keep this practical: for mortgages, secured loans, or anything with tax or legal rules, consult a qualified adviser and check the lender’s loan estimate or your local regulator. This is information, not financial advice.
What the calculator is really telling you
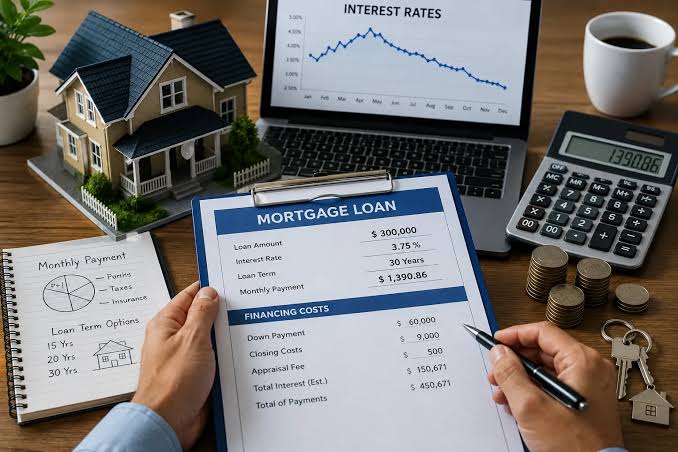
A refinance calculator answers a break-even question, not a “should I feel good about this?” question. It compares your current loan with a new one and shows how long it takes for monthly savings to pay back the upfront cost of switching.
That frame is the right one because refinancing usually has friction. Depending on the loan type and country, the new loan may include origination fees, appraisal costs, title work, discharge fees, application fees, or other charges. Some lenders roll those into the loan balance; others make you pay them at closing. A calculator cannot make those costs disappear. It can only spread them across time and show when the lower payment starts to matter. Cold math. No magic.
The trap is assuming a lower monthly payment automatically means a better deal. It does not. A 30-year refinance can trim the payment and still cost more overall if it resets the clock and adds many extra months of interest. Use the calculator to compare total interest, total fees, and the length of time you plan to keep the loan.
The most important input is not the rate alone. It is the gap between your current rate and the new one, the size of the upfront costs, and how long you expect to keep the loan. If you may move, sell, pay off, or refinance again in a year or two, the math changes fast.
When does refinancing make sense?
Refinancing makes sense when the break-even point is comfortably shorter than the time you expect to keep the loan. That is the simplest rule I trust.
For a mortgage, auto loan, or personal loan, I would look at four things first: the rate drop, the fees, the remaining term, and whether the new term is shorter or longer. A meaningful rate drop on a large balance can matter even if fees are not tiny. A small rate drop on a small balance often does not. In 2024, the average 30-year fixed mortgage rate was often above 6%, so a half-point or one-point drop could matter if the balance is large enough and you keep the loan long enough.
The calculator should help you spot the cases where refinancing is doing real work:
- It lowers the interest rate enough to overcome the closing costs within your planned ownership period.
- It shortens the term without making the payment unmanageable.
- It converts a variable rate into a fixed rate when stability matters more than squeezing out the last bit of monthly savings.
- It removes a co-borrower, changes the loan structure, or lets you move from a risky payment setup into something simpler.
It should also show you when refinancing is weak. If the savings take longer than you will keep the loan, the deal is usually poor. If the new term is much longer, the monthly payment may look better while the total interest quietly rises. If your credit has improved only a little, a refinance may not move the rate enough to justify the paperwork and fees.
A generic article usually misses this: refinancing is not one decision. It is a cluster of choices about cost, time, and risk. A calculator works best when it forces those choices onto one screen.
Current loan vs new loan: the part that actually matters
The current loan wins when you are far enough into repayment that the remaining balance is falling and the rate gap is too small to matter. The new loan wins when it can cut interest fast enough to beat the switching cost before you stop caring.
Here is the head-to-head I would use.
| Criteria | Keep the current loan | Refinance into a new loan | Winner for this condition |
|---|---|---|---|
| Upfront cost | No new closing costs | May include fees, points, appraisal, or lender charges | Keep current loan if cash is tight |
| Monthly payment | Stays the same unless your loan adjusts | Can go up or down depending on term and rate | New loan if cash flow relief matters |
| Total interest paid | Higher if the old rate is high | Can be lower if the new rate and term are favorable | New loan if rate drop is large enough |
| Time to break even | No break-even to recover | Must recover refinance costs | Keep current loan if you may move soon |
| Rate type | May be fixed or variable already | Can switch fixed to variable or vice versa, depending on product | New loan if rate risk is the main problem |
| Term length | Original amortization continues | Term can reset, shorten, or extend | Keep current loan if you do not want the clock reset |
| Credit sensitivity | No new credit underwriting event | Usually requires fresh credit review | Keep current loan if credit is fragile |
| Flexibility | You stay with the existing servicer and terms | New documents, new payment setup, possible prepayment rules | Keep current loan if simplicity matters |
| Balance size | Savings may be modest on a small remaining balance | Bigger balances amplify rate savings | New loan if the balance is still large |
The most useful row is the break-even time. If the calculator cannot show that clearly, it is not doing the job. I would not rely on a refinance that “feels cheaper” but takes years to pay for itself unless the non-math reason is strong, like moving from variable to fixed or eliminating a payment structure you cannot live with.
When the calculator says “yes,” here is why
The new loan wins for borrowers who can name the reason in one sentence. If you cannot do that, the refinance is probably too vague.
A strong refinance case often looks like this:
- Your current rate is clearly above what the market offers for your credit profile.
- Your remaining balance is large enough that a rate drop saves real money.
- The upfront fees are modest relative to the balance, or they are paid in a way that does not erase the gain.
- You expect to keep the loan long enough to cross the break-even point.
- The new structure solves a problem, such as payment instability or a looming rate reset.
This is where a calculator earns its keep. It lets you test combinations: lower rate with 15-year term, lower rate with 30-year term, cash-out refinance, no-cash-out refinance, or switching from variable to fixed. Those are not cosmetic differences. A 15-year loan can cut interest but raise the payment. A cash-out refinance can free cash for a specific use, but it also increases the amount you owe and may lengthen repayment.
The weakness is simple: calculators can make the monthly number look more important than it is. A lower payment can hide a worse total cost, especially if the new term is longer. I would skip any refinance that only “works” because it stretches debt over many more months and does not solve a genuine problem.
Who this is for: borrowers with enough remaining balance and enough time left in the loan to recover the costs, and who want a concrete improvement in either cost or structure, not just a prettier payment.
When keeping the current loan is the smarter move
The current loan wins when the refinance savings are too thin, the payback period is too long, or your future is too uncertain to justify a new contract.
This is the side many articles soften, but I won’t. Refinancing is often a bad fit for people who plan to move, sell, or pay off the debt soon. It is also weak when the balance is already low. A 0.5-point rate drop on a small remaining balance may sound nice and still save very little after fees.
There are other warning signs. If the refinance resets a long amortization schedule, you may lower the payment while increasing the number of months you pay interest. If the new loan has prepayment penalties, rate-lock fees, or points, those can delay or erase the benefit. If your credit score has not improved enough to qualify for a meaningfully better rate, the calculator may simply confirm what the lender already knows: the offer is not strong enough.
I also watch for behavioral mistakes. Some people refinance a credit card or personal loan into a longer unsecured loan and then run the old balance back up. The calculator may show immediate breathing room, but the household budget is still under strain. In that case, the refinance solves the symptom, not the habit.
Who should skip it: anyone with a small balance, a short time horizon, uncertain income, or a refinance offer that only saves money after several years.
The exception cases that flip the answer
Refinancing can still make sense in a few situations that break the usual rules. These are the cases that change the verdict.
Since a rate-type switch can justify a refinance even when the pure savings are modest, the calculator is only part of the decision. If you are moving from variable to fixed and want payment stability, the value comes from reducing rate shock, not just lowering the payment.
Second, if your current loan has a feature you actively need to escape — for example, a balloon payment, a recast you cannot afford, or an adjustable reset that is near — refinancing may be about risk management rather than savings. In that case, the calculator should be paired with a review of the loan terms, not just the math.
Third, if you have enough cash to pay fees but not enough to absorb a higher payment, a refinance into a shorter term may be worth it only if the monthly increase is realistic. A calculator that ignores budget stress is incomplete. A mathematically clean refinance can still be a bad household decision.
On the other hand, some secured loans are tied to tax or legal treatment that changes by country. Mortgage interest rules, deduction rules, and early repayment rules differ by jurisdiction and change often, so consult a qualified tax or legal professional before acting. A refinance that looks attractive on paper may have a different after-tax result once local rules are applied.
My verdict: which choice makes sense
Choose refinancing if the calculator shows a break-even period shorter than the time you expect to keep the loan, and the refinance also improves something concrete — rate, term, or payment stability. Choose the current loan if the savings are small, the fees are high, or you may exit the loan before the break-even point. Neither choice is strong if the only reason is a lower monthly payment and you cannot explain how the total cost changes.
That is the cleanest call I can give. If the numbers do not produce a clear win on cost or risk, keep the loan you have.
What a good refinance calculator must include
A good calculator must include the current balance, current rate, remaining term, new rate, refinance fees, and the new term. Without those, the result is too optimistic.
I would also want a break-even result in months, not just a new payment figure. If a calculator only shows payment reduction, it is incomplete. If it lets you compare a 15-year term against a 30-year term, even better. That comparison often reveals whether you are actually saving money or just stretching debt.
A strong calculator should also let you add points or upfront costs separately from the loan amount. Those costs matter because they change the true break-even date. Some calculators also show total interest paid over the life of each loan, which is useful, but I would still treat it as secondary to the break-even period if your plan is to move or sell. For a mortgage refinance, CFPB guidance on closing disclosures and loan estimates is a useful benchmark, and your lender should show these numbers clearly.
If you are comparing offers from different lenders, check whether the quoted rate depends on points, autopay, or a specific credit tier. Rate quotes often have conditions. In a refinance, the fine print matters as much as the headline number.
FAQ
How do I know if refinancing is worth it?
It is worth it when the savings or risk reduction outweigh the fees before you expect to leave the loan. A break-even calculation is the first filter. For example, a $4,000 refinance cost recovered over 24 months means about $167 a month in savings.
Is a lower monthly payment always a good sign?
No. A lower payment can come from a longer term, and a longer term can increase total interest even when the payment feels easier. On a $250,000 mortgage, even a small term extension can add thousands in interest.
Should I refinance just to get a lower rate?
Only if the rate drop is large enough to cover the refinancing cost and you plan to keep the loan long enough to benefit. If not, the headline rate is not enough.
Does refinancing always involve closing costs?
Not always in the same form, but there are usually costs somewhere in the process, such as lender fees, appraisal charges, or points. Check the loan estimate carefully.
Can I refinance more than once?
Sometimes, depending on lender rules and local regulations, but each refinance has a cost. Repeating the process only makes sense if each new loan produces a real improvement.