Last updated: September 10, 2026
Key Takeaways
- A 6.5% APR over 36 months and the same 6.5% APR over 60 months are not equivalent offers.
- A term that is 50% longer can produce more than 50% more interest, depending on rate and structure.
- If a $500 fee is added to the balance, interest is charged on that fee too; if it is paid upfront, it may not be.
- Keep the rate and principal identical and compare, for example, 36 months versus 60 months, or 15 years versus 30 years.
Compare two loans with the same headline rate, and the term can quietly change the bill. The monthly payment may look friendlier. The total cost? Not so friendly.
If you are comparing loans, the loan term usually affects both your monthly payment and your total interest paid. Longer terms often lower the payment but increase the total interest because the balance stays outstanding longer. Shorter terms usually do the opposite. This guide explains how to compare loan terms, what to check in the disclosure, and where the simple rule can break down.
I am writing this as information, not financial advice. A qualified adviser should be consulted for your circumstances, especially if the loan has unusual fees, penalties, or rate changes.
Who this applies to, and what you need to know first
This applies to anyone comparing fixed-term loans where interest accrues on a remaining balance over time: mortgages, car loans, personal loans, and many student loans. It assumes you already know the basic parts of a loan offer: principal, interest rate, and repayment term. It also assumes the loan may have a fixed rate or a variable rate; if the rate can change, the term still matters, but the final interest cost is less predictable.
Amortization is the key term here. It means the loan is repaid in scheduled installments that split each payment between interest and principal. Early in an amortizing loan, a larger share of each payment goes to interest. Later, more of it goes to principal. That is why the length of the term matters so much.
Not every loan fits this pattern, though. Balloon payments and negative amortization need separate treatment because the term alone does not tell the full cost story. A balloon payment is a large final payment due at the end; negative amortization means the balance can rise instead of fall. Different beast.
This article is not for someone trying to choose between loans with very different fee structures, balloon payments, or negative amortization. Those loans need separate analysis because the term alone does not tell the full cost story. A balloon payment is a large final payment due at the end; negative amortization means the balance can rise instead of fall.
One thing to keep in mind: comparing monthly payment alone can mislead you. A 12-month loan and a 60-month loan can both “fit” the budget, but they do not cost the same. The longer one usually charges interest for far longer.
Why a longer term usually costs more in interest
A longer loan term usually costs more because the lender collects interest on a balance that declines more slowly. On most standard installment loans, each month’s interest is calculated on the unpaid principal balance. Stretch repayment from 24 months to 72 months, and you are not merely spreading the same cost across more payments; you are leaving more principal outstanding for longer.
Same rate. Different outcome. A 6.5% APR over 36 months and the same 6.5% APR over 60 months are not equivalent offers. APR, or annual percentage rate, is the yearly cost of borrowing expressed as a rate; it can include some fees depending on the product and country. The longer term gives interest more time to pile up.
Think of each payment as doing two jobs. First, it covers that month’s interest. Second, it reduces the principal. When the monthly payment is small, more of each early installment goes to interest and less to principal. The balance stays stubbornly high, which creates more interest next month. The result is not linear. A term that is 50% longer can produce more than 50% more interest, depending on rate and structure.
The common mistake is treating term like a convenience setting only. It is not. It is a price setting, and Consumer Financial Protection Bureau guidance on loan costs emphasizes comparing the total cost of credit, not only the payment. The payment may be easier to handle, but the loan becomes more expensive over time.
That is why lenders often lead with the low monthly payment. Fair enough; people notice it. But the real question is not “Can I make the payment?” alone. It is “How much interest am I paying for the privilege of making that payment smaller?”
How do I compare two loan terms without getting tricked by the monthly payment?
Compare total interest side by side, not just the payment. Use the same principal, rate, fees, and repayment rules. The cleanest comparison is between amortization schedules: tables that show each payment’s split between principal and interest over the life of the loan. See the Consumer Financial Protection Bureau’s explanations of amortization and the Federal Trade Commission’s guidance on comparing loan offers.
Here is the method I would use.
- Write down the exact loan amount. Use the amount financed, not the sticker price. Check whether fees are rolled into the principal. If a $500 fee is added to the balance, interest is charged on that fee too; if it is paid upfront, it may not be.
- Record the rate in the same format. Use APR if you are comparing offers in the same market and the same country, because it is designed to show borrowing cost more consistently. Check whether the rate is fixed or variable. If the rate can reset, the term comparison is less certain.
- Compare terms in whole months or years. Keep the rate and principal identical and compare, for example, 36 months versus 60 months, or 15 years versus 30 years. Check that both loans use the same payment frequency. If one is monthly and the other is biweekly, the comparison needs adjustment.
- Look at the payment difference, then the interest difference. Use the lender’s amortization table, calculator, or disclosure document. Check the total of all payments and subtract the original principal to estimate total interest, excluding any separate fees. If the interest total is not shown, that is a warning sign that the offer is hard to compare cleanly.
- Check whether prepayment is allowed without penalty. Prepayment means paying extra principal before the scheduled end. Check whether extra payments go straight to principal or are applied differently. If there is a prepayment penalty, the shorter effective term may not save as much interest as you expect.
- Test one realistic extra-payment scenario. For example, ask what happens if you pay an extra amount once a year or round up each monthly payment. Check whether the loan recalculates interest on the new balance immediately. If extra payments are held in suspense or applied only to future installments, the benefit may be delayed.
- Inspect the first 6 to 12 payments on the amortization schedule. Early payments reveal how quickly principal falls. Check whether the balance drops slowly or quickly in the first year. If most of the payment is still interest after many months, the term is long relative to the rate and principal.
- Compare total cost, not just interest, if fees differ. Use the annualized cost disclosure required in your market, if available, but check the detail line by line. Check origination fees, document fees, insurance, and closing costs. If one loan has lower interest but much higher fees, the cheaper-looking term may not be cheaper overall.
A good comparison uses the same assumptions for every line. A bad one mixes fixed and variable rates, ignores fees, or compares different payment schedules as if they were identical. No shortcuts here. If you cannot get a clear amortization schedule, ask the lender for one before you decide.
What happens to total interest when the term changes?
Total interest usually falls as the term gets shorter, but the savings depend on the rate, principal, and how the loan is structured. The effect is strongest when the rate is high or the principal is large, because every extra month leaves more balance exposed to interest charges.
For a standard amortizing loan, the relationship is straightforward:
- Shorter term: higher monthly payment, lower total interest.
- Longer term: lower monthly payment, higher total interest.
- Same term, higher rate: higher interest in every month.
- Same rate, more principal: more interest overall.
There is a second effect that people miss. Because principal declines more slowly on a longer loan, the borrower stays “farther from zero” for longer. That means a long term can feel manageable for years while still producing a large interest bill. This is especially visible on mortgages and auto loans with terms that run well beyond the point where the asset may still be useful.
I would be cautious about using the word “always,” because there are exceptions. A low promotional rate for a short time can make the math less obvious. So can loans with interest-only periods, deferred interest, or rate resets. In those cases, the loan term still matters, but it is not the only driver of interest cost.
Need a quick rule of thumb? Ask: “How many months will this balance keep generating interest?” The longer the answer, the more total interest you should expect, all else equal.
When does the standard rule break down?
The standard rule breaks down when the loan does not amortize in the usual way, when the rate changes, or when fees and penalties dominate the cost. In those cases, loan term still matters, but it is not the only thing that determines total interest. See the CFPB for general loan-cost explanations and the FTC for warnings about promotional and deferred-interest offers.
Interest-only period: Your payments cover interest for a set time, often 6 to 60 months, while principal does not fall — the later amortizing period can produce a sharp payment jump, and total interest can end up higher than expected. Get the full schedule, not just the initial payment.
Variable-rate loan: The rate can change at set intervals, such as every 6 or 12 months — the term comparison becomes a moving target because the interest rate may rise or fall. Use conservative assumptions and ask how caps and margins work.
Balloon payment loan: A large final payment is due at the end — the early monthly payment may look low, but the term does not tell you the full payoff burden. Check the balloon size and whether refinancing would be required.
Prepayment penalty: Extra principal payments can trigger a fee — the expected interest savings from a shorter effective term may be reduced or wiped out. Read the penalty window and formula before assuming extra payments help.
Deferred-interest promotion: Interest may accrue from day one but be waived only if the balance is paid in full by a deadline, often 6 to 24 months — missing the deadline can make the loan much more expensive. Treat the deadline as binding, not aspirational, and confirm the terms with the lender or a qualified adviser.
Fees are large relative to the principal: Origination fees, closing costs, or insurance charges add to cost — the “cheaper” rate may not be the cheaper loan. Compare the all-in cost, not just the coupon rate.
These are the situations where I would slow down and read the disclosure page line by line. The loan term is still important, but it is no longer the whole story.
The mistakes people make when they focus only on the monthly payment
The most common mistake is choosing the lowest payment without checking the total interest. The consequence is predictable: you pay more over the life of the loan than you needed to. The correct alternative is to compare total payments and total interest side by side, not monthly affordability alone.
A second mistake is ignoring fees. An origination fee, closing cost, or mandatory insurance premium can make a short-term loan look cheaper than it really is. The consequence is a false comparison. The correct alternative is to calculate the total amount paid, not just the stated rate.
A third mistake is assuming every extra payment reduces interest immediately. Some lenders apply extra money to future installments, not principal, unless you instruct them otherwise. The consequence is delayed or reduced savings. The correct alternative is to confirm the lender’s payment application rules in writing.
A fourth mistake is comparing loans with different compounding or payment frequencies as if they were the same. A biweekly payment plan can shorten the effective term compared with 12 monthly payments, but only if the lender actually applies the extra amount to principal. The consequence is a bad apples-to-oranges comparison. The correct alternative is to use the same schedule and the same compounding basis.
A fifth mistake is forgetting that a longer term can increase the chance of still owing money after the asset has aged. On a car loan, that can mean being underwater, where the balance exceeds the vehicle’s value, for longer. The consequence is less flexibility if you need to sell or replace the asset. The correct alternative is to consider the payoff timeline, not just the payment.
These mistakes are not rare because they are irrational; they are common because the payment is the number lenders highlight. That can be incomplete, so compare the full loan cost before you sign.
How do extra payments change the interest bill?
Extra principal payments can cut total interest materially because they reduce the balance sooner, and interest stops accruing on the amount you already repaid. The size of the effect depends on timing. An extra payment in year one usually saves more interest than the same payment in the final year, because it changes the balance for many more months.
The clean way to think about this is simple: principal repaid early is the most valuable principal. Put $1,000 in early, and you avoid interest on that amount for many remaining periods. Put the same $1,000 in near the end, and most of the interest on it has already been collected.
A lower loan term is not the only way to save interest, because extra principal payments can also shorten the effective term. That does not mean extra payments are always the best choice. If a loan has a prepayment penalty, a variable rate, or a high-cost emergency reserve gap, the calculation changes. The right trade-off depends on the loan contract and your broader financial position.
One useful check is to ask the lender whether extra payments are applied to principal immediately and whether you need to mark them as “principal only.” If the answer is vague, get clarification before sending extra money. A 10-minute call can prevent months of misunderstanding.
For someone comparing terms, the presence of easy prepayment matters. A longer term with no penalty is not the same as a longer term with a stiff penalty. The first gives you flexibility to behave as if the loan were shorter. The second locks in the expensive path.
What should you look for on the disclosure before you sign?
You should look for the loan amount, APR, term, payment schedule, fee schedule, and any prepayment terms before you sign. Those five items tell you whether the term is the main driver of cost or just one piece of a more complicated structure.
The disclosure should let you answer five questions:
- How much am I actually borrowing?
- Over how many months or years will I repay it?
- Is the rate fixed or variable?
- What fees are included in the cost?
- Can I pay extra without penalty?
If the disclosure does not answer those questions clearly, ask before you proceed. For consumer loans in the United States, the CFPB explains how to compare costs and disclosures, and the FTC offers guidance on spotting misleading loan terms. A loan term should be easy to read; if it is not, that is itself a warning sign.
A quick example of how the math works
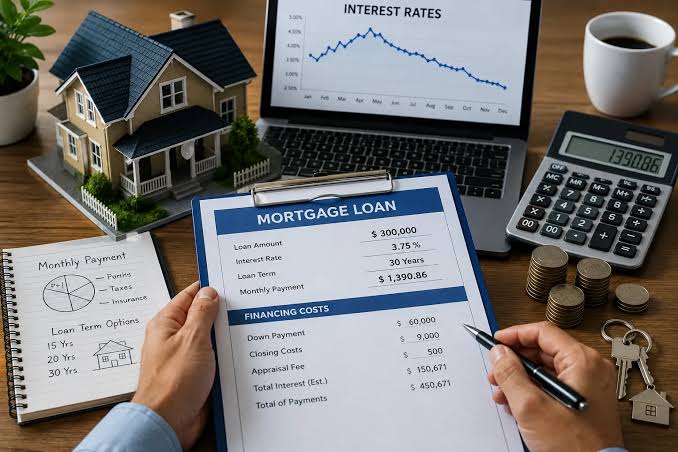
Suppose you borrow $20,000 at a fixed 6.5% APR. If you repay it over 36 months, the monthly payment will be higher, but the balance falls faster and total interest is lower. If you stretch the same loan to 60 months, the monthly payment drops, but you pay interest for two extra years. Over the life of the loan, the longer term usually costs more even though the monthly payment feels easier.
Now suppose the 60-month loan also includes a $500 fee rolled into the principal. Interest is then charged on $20,500, not $20,000. That pushes the total cost up again. The term and the fees work together, which is why comparing payment alone can be misleading.
Make extra principal payments in year one, and some of that interest cost comes back down. The earlier the extra payment, the larger the savings. So the best comparison is not only between terms, but between terms and your likely payment behavior.
Bottom line
Loan terms affect total interest by changing how long the balance stays outstanding. In a standard amortizing loan, shorter terms usually mean less total interest and higher monthly payments, while longer terms usually mean the opposite. The safest way to compare offers is to hold the rate, principal, and fees constant, then compare the total cost and the full amortization schedule.