Last updated: October 21, 2026
Quick Answer: compare at least 8 fields across the loan estimate, closing disclosure, promissory note, amortization schedule, and loan agreement before you sign. That is the core of how to compare loan disclosures before you sign, and it works best when you line up the same numbers on every document. This guide is for a borrower who already has the loan estimate, closing disclosure, promissory note, amortization schedule, and loan agreement in hand and wants to catch mismatches before they become your problem. It is information, not financial advice; a qualified adviser should review your own situation if anything looks unclear or the amounts are large.
What a loan disclosure tells you, and what it does not
A loan disclosure tells you the cost, timing, and obligations of the loan in writing, but it does not tell you whether the loan fits your budget or long-term plan. That distinction matters because the same monthly payment can hide very different fee structures, payment timing, and default terms.
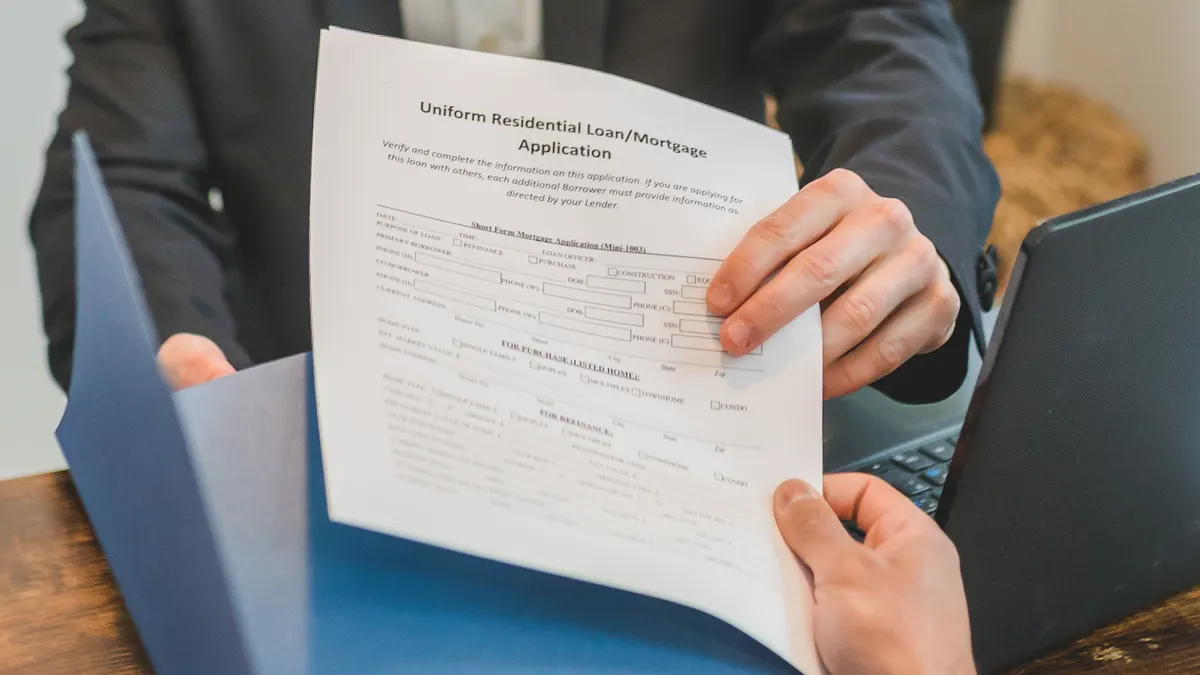
For a mortgage in the United States, the two most familiar disclosure documents are the loan estimate and the closing disclosure. The loan estimate is the early summary you receive after application; the closing disclosure is the final version presented before consummation, usually at least 3 business days before closing in many mortgage transactions under U.S. rules. A promissory note is different again: it is the document where you promise to repay. The amortization schedule is the payment-by-payment map of principal and interest over time. The loan agreement, if there is one, may add covenants, conditions, and remedies.
The core job is not to read each document in isolation. It is to compare the same data points across them: loan amount, interest rate, term, payment timing, fees, points, escrow, and any clauses that change what happens if you are late or pay early. That comparison is where mismatches show up.
This page belongs on the hub for loan comparison methods and calculators, but it focuses on the documents, not on choosing between products.
Which loan disclosure should I compare first?
Start with the loan estimate, then compare it to the closing disclosure and the promissory note side by side. That sequence shows you whether the lender changed the price, the payment structure, or the legal obligations between the offer stage and the final signing stage.
Use a 3-column layout if you can: document name, field name, and value. Then compare these items in the same order on every page:
- Loan amount. Match the principal on the loan estimate, closing disclosure, and promissory note. If one says $250,000 and another says something different, stop and ask why. A change here can alter the payment, fee math, and escrow amounts.
- Interest rate and rate type. Check whether the rate is fixed or adjustable, and whether the note names an index, margin, or adjustment cap. If the loan estimate shows one structure and the note shows another, that is not a small edit.
- Monthly payment. Compare the payment on the loan estimate with the amount due in the note and amortization schedule. Verify whether the payment includes principal, interest, taxes, insurance, or mortgage insurance. A mismatch often means you are comparing different components.
- Loan term. Confirm the number of months or years. A 30-year term and a 15-year term can look similar on paper for a single payment, but the total structure is not the same.
- Fees section. Compare origination fee, discount points, underwriting fees, appraisal, title charges, and lender credits. The fees section should not change categories without a clear reason.
- Prepayment language. Read whether the note or agreement mentions a penalty or conditions for early payoff. If this appears in one document but not another, ask for the exact controlling clause.
- Escrow and reserves. If the closing disclosure includes escrow for taxes and insurance, verify the initial deposit and monthly collection amounts. A missing or extra escrow line can change your cash needed at closing.
- Default and late-payment terms. Check when a payment is considered late, what fee applies, and whether there is a grace period. These terms often live in the note or agreement rather than the summary form.
If you use a calculator later, use these verified inputs first. A calculator built on the wrong fee or term only produces a cleaner mistake.
How do I compare the loan estimate with the closing disclosure?
You compare them line by line, with special attention to any item that moved outside the allowed tolerance, changed from optional to required, or appeared only in the final papers. The loan estimate is a forecast; the closing disclosure is the final bill and final legal terms.
Begin with page 1 of each form and work across the same headings. Then move to the detailed fee page, because that is where surprises usually hide. The terms that deserve the closest comparison are the ones that affect cash due at closing and the ongoing cost of the loan.
Look first at the origination fee. That is the lender’s charge for making the loan, usually shown as a dollar amount or as points. If the loan estimate says one amount and the closing disclosure says another, ask for the exact reason and whether any changed circumstance explains it. Do the same with discount points, lender credits, appraisal fees, recording fees, and title-related charges.
Then compare the rate and payment. A small change in interest rate can move the payment, but the document should show that change clearly. If the payment on the closing disclosure includes escrow items and the estimate did not, compare the escrow line items rather than assuming the numbers are equal. The payment line should not be a guessing game.
Also compare the dates. A closing disclosure is usually delivered before signing, and the loan estimate is earlier in the process. If the timing is compressed or the final document arrives too late to review, that is a process problem, not a math problem. A rushed signature can hide a document that differs from the offer summary in a way you would have questioned with another hour to read it.
If any fee rose, ask whether it is one of the items that can legally change or whether it was simply misstated earlier. The answer should be written, not implied.
What do the promissory note and loan agreement add?
They add the terms that govern repayment, default, and enforcement, and those terms can matter more than the summary pages when something goes wrong. The promissory note is the borrower’s promise to repay; the loan agreement may add covenants or extra conditions beyond the note.
Read the note for five things: payment amount, payment date, interest calculation, late charges, and what happens on default. Then read the loan agreement for any clauses that make the lender’s rights broader than the summary suggests. A loan agreement can contain conditions about insurance, collateral, financial reporting, or events that trigger default even if you are current on the payment.
This is where readers often make a mistake: they compare only the payment and the APR-style figures and skip the fine print. But the note controls the promise to pay, and the agreement can control the consequences of missing another document requirement. For example, a clause requiring proof of insurance by a certain date is not the same as a simple monthly payment obligation.
Also check whether the note says the interest rate can change. If it is adjustable, the note should explain the index, the margin, the adjustment interval, and the caps. If those terms are not in the summary, that is a signal to slow down, not to assume the summary is complete.
A clean comparison here is simple: if the summary says one thing and the note says another, the note usually carries the legal weight. If the note is unclear, ask for a written explanation before signing.
How can I spot a mismatch in fees, terms, or payment structure?
You spot a mismatch by comparing the same field name across documents, then checking whether the difference is a real term change or just a formatting change. A 3-line fee table often reveals more than a 20-page packet read straight through.
Use this order:
- Fee name. Make sure “origination fee,” “underwriting fee,” and “processing fee” are not being swapped around under different labels.
- Fee amount. Verify the number and whether it is charged upfront, financed into the loan, or deducted from proceeds.
- Payment timing. Check whether the first payment date changed, since a 30-day shift affects cash flow even if the monthly amount stays the same.
- Amortization schedule. Confirm the first 3 to 12 payments show the expected split between principal and interest. Early payments are usually interest-heavy on amortizing loans, so a schedule that looks reversed needs explanation.
- Escrow setup. See whether taxes, homeowners insurance, or mortgage insurance are included.
- Balloon or final payment. If there is a large final payment, it should appear in the note and the schedule, not just in a footnote.
A mismatch can be harmless only if it is explained in writing. A common example is a fee that appears in one document because it is rolled into closing costs, while another document separates it out. That still needs to reconcile to the same total.
If the closing disclosure and note disagree on a core term like principal, rate, or maturity date, do not treat it as a clerical typo until someone shows the correction in writing and, if needed, a qualified professional confirms the fix.
When should I stop and get qualified help?
You should stop when the documents disagree on a core term, when you do not understand the default language, or when the lender cannot explain a change in writing. Those situations can affect your money, your title, or your legal obligation, and they are not good candidates for a quick guess.
The loan amount changes between the estimate and the final papers: That can change the payment, fees, and total amount financed — pause and ask for a written correction before signing.
The interest rate or rate type changes without a clear explanation: A fixed-rate loan that turns into an adjustable-rate loan, or vice versa, changes the risk profile — stop and have a qualified adviser review the note.
The closing disclosure arrives too late to review carefully: Time pressure increases the chance of missing a fee or term change — ask for more time and compare the forms before you sign.
The promissory note contains late fees, default clauses, or prepayment language you do not understand: Those terms control what happens after signing — get a lawyer or other qualified professional to explain the legal effect.
The fee section includes items that were not on the loan estimate and were not previously disclosed: That may signal a pricing or compliance issue — request a line-by-line explanation and do not rely on verbal assurances.
The amortization schedule shows a balloon payment or unusual payment pattern: The loan may not behave like a standard installment loan — verify the schedule and do not assume monthly payments tell the whole story.
This is also the point where a mortgage broker, attorney, housing counselor, or other qualified adviser may be worth the call, depending on the country and loan type. I cannot tell you which professional is right for your case from a form alone.
What mistakes do people make most often?
The most common mistake is comparing totals without comparing line items, and that can hide a changed fee or term. A glossy summary may still be wrong in the exact place that matters.
- They compare only the monthly payment. The consequence is missed fee changes or a longer term that makes the loan more expensive over time. The better move is to compare the payment, term, and fee section together.
- They ignore the promissory note because it looks dense. The consequence is missing default language or an adjustable-rate clause. The better move is to read the note’s repayment and default sections first, then the rest.
- They assume the loan estimate is final. The consequence is surprise at closing when the figures differ. The better move is to treat the estimate as a draft and verify the closing disclosure before signing, with help from a qualified adviser if anything is unclear.
- They skip the amortization schedule. The consequence is not seeing how much of the early payment goes to interest or whether the final payment differs. The better move is to inspect at least the first 12 months and the final month.
- They do not ask for written clarification. The consequence is relying on a verbal explanation that is easy to forget and hard to prove later. The better move is to request an email or revised form that reconciles the numbers.
- They compare the wrong version of a document. The consequence is signing based on an outdated draft. The better move is to confirm the document date and version number before you read it.
The problem is rarely one dramatic mistake. It is usually three small ones that all lean in the same direction.
What if the loan is not a standard mortgage?
Then the same comparison method still helps, but the documents may be named differently and the rules may differ by country, lender, and product type. Personal loans, auto loans, business credit, and some private loans may not use a loan estimate or closing disclosure at all, yet they still have a disclosure, a note, and a fee schedule of some kind.
Adjust the comparison to the documents you actually have. For an auto loan, the fee disclosure and retail installment contract matter more than a mortgage-style closing disclosure. For a private student loan, the repayment terms and deferment language may matter more than an amortization schedule alone. For business credit, a guarantee or security agreement can change the risk far beyond the payment amount.
The method does not change: compare the same field across the offer summary, the repayment contract, and the final signed version. What changes is the terminology. One lender may call a charge an “origination fee,” another may call it a “processing fee,” and another may split it into two lines. The label is less important than the actual dollar effect and the legal consequence.
This is also where country-specific rules matter. Disclosure timing, fee naming, and required forms vary widely. If you are outside the United States, do not assume a mortgage disclosure checklist from another country maps cleanly to your loan.
If your loan includes collateral, a guarantor, or a variable rate, read those terms twice before signing. Those features can change the risk in ways the payment line does not show.
Key Takeaways
- Compare the same fields across the estimate, final disclosure, note, and schedule, not just the monthly payment.
- The biggest red flags are changes in principal, rate type, term, fee structure, escrow, and default language.
- A 3-column comparison table can expose mismatches faster than reading each document separately.
- If the documents conflict on a core term, get written clarification before you sign.
Drafted with AI; not yet reviewed by a person.