Last updated: October 24, 2026
Key Takeaways
- A joint loan offer is one credit deal for two applicants who share legal responsibility for repayment.
- Lenders judge a joint loan offer by affordability rules and the risk in both borrowers.
- The best comparison method is to use one template, then test each payment against a real household budget.
- Check the budget, each borrower’s credit file, and how the lender handles joint income before trusting the final offer.
A joint loan offer is compared by looking at the same loan terms against both borrowers’ incomes, credit files, and liability, not by looking at one person in isolation. This loan comparison guide for comparing offers from multiple borrowers in one household is for two people in one household who plan to apply together as joint applicants and want to understand which part of the offer is driven by income combination, which part is driven by credit, and where shared debt responsibility changes the decision.
Who this applies to, and what a joint loan offer actually is
A joint loan offer is a single credit offer made to two applicants who apply for the same debt and share legal responsibility for repaying it. This guide applies when both people live in the same household, both expect to be named on the agreement, and both want to compare offers before signing. It assumes the reader already knows the basic loan figures, such as the amount borrowed, term, monthly payment, and any fee or APR, which is the annual percentage rate used to describe the cost of credit over a year.
This is information, not financial advice. Loan rules, disclosure standards, and affordability checks vary by country and lender, so a qualified adviser should be consulted for your own situation if the numbers are tight or the contract is complex. The Consumer Financial Protection Bureau explains how lenders consider ability to repay, and MoneyHelper explains joint borrowing and shared responsibility.
The important point is that a joint loan offer is not just “two incomes mean a better deal.” Lenders usually review the combined household income, but they also look at each applicant’s credit profile, existing commitments, and repayment history. A strong second applicant can help if the lender allows income pooling and both borrowers qualify. A weaker second applicant can also drag down the offer, especially if one file shows missed payments, high utilization, or recent credit applications.
This page is about joint applicants, co-applicants, household income, liability, and application review. It does not cover comparing a loan with a cosigner or co-borrower, secured versus unsecured borrowing, or which type of lender is cheapest. Those are different comparisons and deserve their own decision path. If those choices matter in your case, consult a qualified adviser before you compare offers.
If you want a method for comparing numbers across offers, this guide fits alongside the hub on loan comparison methods and calculators, where the mechanics are broader and the category-level comparisons live.
How do lenders compare a joint loan offer?
Lenders compare a joint loan offer by checking whether the combined application meets their affordability rules, then pricing the loan off the risk they see in both borrowers. The headline rate can look simple, but the decision is usually built from several layers: income, debt-to-income ratio, credit history, payment capacity, and the lender’s own policy on joint liability.
The first thing to compare is who the lender treats as the main risk driver, and if that is unclear, consult a qualified adviser. Some lenders weight the higher earner more heavily for affordability, while others focus on the weaker credit profile because both applicants are jointly and severally liable. Joint and severally liable means each borrower can be held responsible for the full debt, not just half. If one person cannot pay, the lender can pursue the other for the entire balance according to the contract.
To compare offers properly, read the terms side by side and isolate the variables that may differ because the application is joint:
- Same loan amount, same term, same repayment type.
- Same borrower names and order on the application, if the lender uses order in its review.
- Same fixed or variable rate structure.
- Same fees, especially origination fees, late fees, and early repayment charges.
- Same assumptions about household income and outgoings.
A useful comparison is not “which monthly payment is lower?” alone. It is “which offer is cheaper over the full term, which one creates less repayment strain, and which one leaves the household with more margin if one income drops for a few months?”
External sources help here. The Consumer Financial Protection Bureau explains how lenders consider ability to repay in lending decisions, and the UK’s MoneyHelper explains joint borrowing and shared responsibility in plain language. Those resources are useful because they separate the marketing language from the legal structure.
How to compare joint loan offers step by step
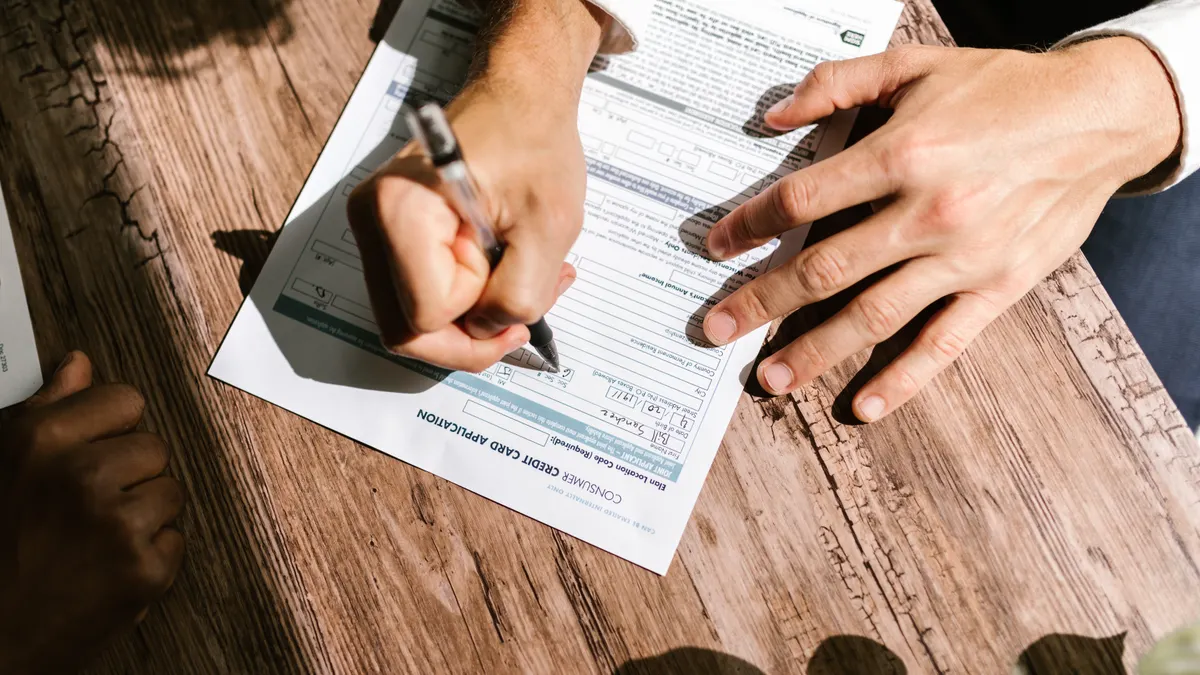
The cleanest way to compare joint loan offers is to put every offer into the same template, then test the payment against a realistic household budget before anyone signs. Do not compare one lender’s headline APR against another lender’s monthly payment; compare like with like.
- List the offer basics on one page. Record the loan amount, term in months, APR, payment frequency, fees, and whether the rate is fixed or variable. Verify that all offers use the same borrowing amount and the same repayment schedule. A mismatch of even 12 months in term makes the monthly payment look better than it really is.
- Check whose income the lender counted. Write down each applicant’s gross and net income, plus any other income the lender accepted, such as regular bonuses or pension income. Verify whether both incomes were combined fully or capped. A problem sign is an offer that looks generous but was built on income the lender may not treat as reliable at renewal or in a later stress check; if that applies, consult a qualified adviser.
- Separate the credit profile effects. Note each borrower’s credit score band, recent credit searches, missed payments, and outstanding revolving balances. Verify whether one application was priced as if the weaker profile drove the decision. A red flag is a rate that is much worse than either borrower expected, because the lender may have priced in the riskiest file on the application.
- Calculate the real monthly commitment. Add the loan payment to any required insurance, account fee, or package fee if the lender bundles them. Compare that total against household surplus after rent or mortgage, utilities, food, transport, and existing debt. A problem appears if the payment only fits when a variable income stream arrives on time every month.
- Test the household against a one-income scenario. Remove one applicant’s income from the budget for 3 to 6 months and see whether the payment still fits. Verify that essential bills still get paid first. If the loan breaks the budget in that scenario, the offer is fragile even if the initial approval looked fine.
- Read the liability clause line by line. Check whether the agreement says both borrowers are jointly liable, severally liable, or jointly and severally liable. Verify who can request changes, who can make overpayments, and who can request settlement figures. A problem sign is any ambiguity about who owes what after separation or household change.
- Compare total cost, not just the rate. Add up all payments over the full term and include mandatory fees. Compare that to the amount borrowed to see the total cost of credit. If one offer is slightly lower monthly but longer by 24 months, it may cost more overall.
- Check the exit conditions before choosing. Look for early repayment charges, fees for changing payment dates, and rules for removing a borrower. Verify whether the loan can be repaid early without a penalty or whether the contract makes exit expensive. A problem sign is a loan that is affordable only if nothing changes.
Once those steps are complete, the better offer is usually the one that balances price with survivability. A lower APR is useful, but not if the payment only works when both incomes stay exactly as they are for the full term.
What should you check before you compare the final offers?
You should check the household budget, the credit file for each borrower, and the lender’s treatment of joint income before you trust any final offer. That is the shortest answer, but the details matter.
Start with the budget. Use monthly figures, not annual optimism. If one borrower is paid weekly and the other monthly, convert everything to a monthly view and keep a 10% buffer for irregular bills if that buffer exists. If there is no buffer, the loan is already too tight to compare cleanly.
Next, check the credit files for both applicants. A joint application can be influenced by a single late payment or a thin file. “Thin file” means the lender has little repayment history to judge. If one person has limited credit history and the other has strong history, the lender may still rate the pair more cautiously than the strong borrower expects. That does not mean the application cannot work; it means the offer may reflect the weaker file.
Then look at debt responsibility. If the agreement creates joint and several liability, every borrower should assume the lender may pursue either one for the full amount. That matters in household planning, especially if the couple keeps separate finances. It also matters if the relationship ends during the term. The contract does not end just because the household arrangement changes.
Finally, check whether the lender asks for documentation from both parties: payslips, bank statements, tax returns, or proof of address. Many lenders ask for 2 to 3 months of statements and recent payslips, though exact documents vary. Missing or inconsistent paperwork can delay review or trigger a lower offer, so if the statements do not match the application, consult a qualified adviser.
For readers who want the comparison framework itself, the broader calculator-based method on the loan comparison methods and calculators hub is the right companion piece. This page focuses on what is different when two borrowers sit inside one application.
When a joint loan is the wrong tool
A joint loan is the wrong tool when the application hides unequal risk, unstable income, or a disagreement about liability. In those situations, comparing offers does not fix the structure.
One borrower has recent missed payments or collections: the weaker credit file may price the whole offer higher or block approval — get the problem assessed before applying together.
One income is variable and the payment depends on overtime, commissions, or tips: the affordability test may fail in a slow month — compare using the base income only, not the best month.
The household budget has no room for a 2- or 3-month shock: the loan may fit today but not survive a disruption — slow down and rebuild the budget first.
The borrowers do not agree on who pays what if one person leaves the household: the liability is still shared — do not sign until the repayment plan is written out and understood.
One person wants the loan but the other is only signing to improve terms: that creates an unequal burden — get qualified advice before one person takes on legal responsibility for another’s spending.
The lender’s review depends on income that cannot be documented: unverifiable income can be excluded or discounted — compare only the version of the offer that is supported by records.
These are not abstract cautions. They are the points where a joint loan stops being a pricing exercise and becomes a contract problem. If the structure is wrong, the cheapest offer can still be the worst fit.
The mistakes people make when comparing joint offers
The most common mistake is comparing the rate while ignoring liability. A lower APR can hide a longer term, a larger fee, or stricter repayment terms. The fix is simple: compare total repayment, monthly commitment, and exit conditions together.
A second mistake is assuming both incomes are treated equally. Lenders do not have to value each applicant the same way. One borrower’s income may be fully counted, partially counted, or discounted if it is irregular. If the household assumes both salaries will carry equal weight and the lender disagrees, the comparison becomes misleading.
A third mistake is focusing on the stronger credit profile. If one applicant has excellent credit and the other has a weaker file, the better borrower may assume the offer should reflect the stronger score. In joint lending, the offer can be pulled toward the weaker profile because the lender is taking on the risk of both.
A fourth mistake is ignoring what happens if one borrower stops paying. That can turn a manageable monthly payment into a collection issue for the other borrower. The correct approach is to test the budget as if only one income remains, even if that scenario feels unlikely.
A fifth mistake is comparing offers without checking fees that appear later. A loan with a modest monthly payment can still be expensive if it carries an origination fee, an account fee, or an early repayment charge. The right comparison is the whole contract, not the headline.
A sixth mistake is applying before both people have agreed on the borrowing purpose and exit plan. If one person expects to refinance in a year and the other expects to keep the loan for the full term, the comparison will reward the wrong offer. The cleaner alternative is to agree on the term, the repayment source, and the fallback plan before any application is sent.
What changes in edge cases?
The standard comparison method needs adjustment when income, credit history, or household structure is unusual. In those cases, the normal “lowest APR wins” rule often fails.
If one borrower is self-employed, compare offers using the documents the lender actually accepts, usually tax returns or accounts rather than projected income. Self-employed income can be averaged or discounted, so the household should compare the lender’s documented figure, not the highest recent month.
If one borrower is new to credit, expect a thinner file and possibly a narrower set of offers. The comparison should then focus more heavily on affordability and contractual clarity than on chasing the lowest advertised rate.
If the household income includes benefits, rental income, or irregular bonuses, confirm whether the lender counts them at all and, if so, at what portion. Some lenders accept these sources, but often not at 100% of face value. Comparing offers without that adjustment gives a false picture.
If the borrowers live together but keep separate finances, the application still creates shared liability if both names are on the loan. The household can compare offers separately first, then compare the joint offer against those individual offers to see whether the shared contract actually adds value.
If the loan is large relative to income, the lender may require extra documentation or a stricter stress test. In that case, a short comparison sheet is not enough. The right move is to compare the lender’s stress assumptions, not just the quoted payment.
For readers comparing multiple loan methods, the key is this: the joint application is judged by the pair, but repaid by the household. That difference matters more than the marketing language suggests.
What does a good comparison look like in practice?
A good comparison shows, on one page, which offer is cheapest, which offer is easiest to carry, and which offer creates the least damage if circumstances change. That comparison usually includes at least 5 figures: amount borrowed, APR, monthly payment, term, and total repayment.
It also identifies the point of failure. If the household can cover the payment only while both incomes remain stable, the offer is less resilient than one that still works after a temporary drop in earnings. If the agreement depends on one borrower’s bonus or overtime, the comparison should say so plainly. If the contract includes a 24-month longer term, the comparison should show the extra cost plainly too.
A strong comparison is not the one with the most optimistic assumptions. It is the one that still makes sense when one income slips, a fee appears, or the relationship changes. That is the real test for joint borrowing.
Drafted with AI; not yet reviewed by a person.