Last updated: September 10, 2026
Key Takeaways
- Verify the ranking still holds if you change one assumption, such as paying off 12 months early.
- A fee on a loan you refinance in 12 months is far more expensive relative to how long you kept the money.
- A 1% origination fee on a $50,000 loan is a different animal from a $300 flat fee.
- A late fee after 15 days is different from one after 1 day.
Table of Contents
- What these three fees actually do
- How do I compare loan origination fees, late fees, and prepayment penalties?
- Which fee matters most depends on how you will use the loan
- What should I check before I compare the offers?
- When should I stop and get qualified help?
- The mistakes people make, and what those mistakes cost them
- How do edge cases change the comparison?
Loan origination fees, late fees, and prepayment penalties are easiest to compare when you reduce them to one question: how much will this loan really cost if I borrow the amount I need and repay it on the schedule I expect? That’s the right lens whether you are looking at a mortgage, a personal loan, a small-business loan, or another consumer credit product. Clean. Brutal, really.
This is information, not financial advice. Loan terms, disclosure rules, and fee caps vary by country and by product type, so for your own situation I would confirm the documents with a qualified financial adviser, attorney, or loan officer who is licensed where you live.
What these three fees actually do
Upfront charges raise the starting cost, late fees punish missed or overdue payments, and prepayment penalties can make early payoff expensive. They hit different moments in the loan’s life, which is why a low advertised rate can still turn into the pricier option once fees are layered in.
An origination fee is the charge the lender takes for making the loan or processing the application. It may be flat or tied to the loan amount. A late fee kicks in when a payment misses the deadline, often after a grace period written into the contract. A prepayment penalty is a charge for paying off part or all of the loan early, or for refinancing before a set date.
The mistake I see most often is comparing only the interest rate or only the monthly payment. That leaves out the part that hurts at signing, the part that hurts when cash is tight, and the part that bites if you refinance or sell. A loan with a 1% origination fee, a strict late fee, and a prepayment penalty can cost more overall than a loan with a slightly higher rate and none of those add-ons. Sneaky little trap.
Read the fee rules together with the amortization schedule, which is the table showing how each payment is split between interest and principal over time. That schedule matters because a penalty on a loan balance of $200,000 is not the same as a penalty on $20,000, even if the percentage looks similar.
How do I compare loan origination fees, late fees, and prepayment penalties?
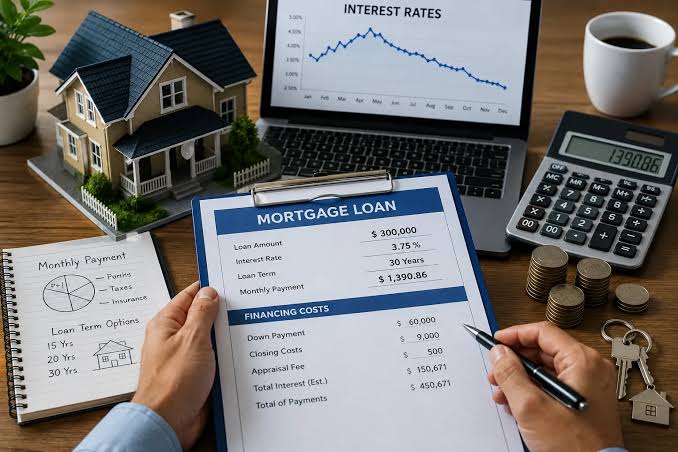
Start by turning each fee into a likely dollar cost under your own repayment plan, then rank the loans by total cost under the scenario you expect. The cleanest way is to use the loan estimate, promissory note, or equivalent disclosure, and fill in three columns: upfront cost, timing risk, and early-repayment cost. For guidance on comparison shopping and mortgage disclosures, see the Consumer Financial Protection Bureau’s loan estimate resources and compare them with your own documents.
-
Write down the principal, term, and rate for each loan. Use the exact amount you plan to borrow, such as $15,000 over 36 months or $300,000 over 30 years. Verify: the contract states the same loan amount and term you expect. Problem sign: the offer assumes a larger loan, a teaser rate, or a longer term than you actually want.
-
Convert the origination fee into a dollar amount. If the fee is a percentage, multiply it by the loan amount; if it is flat, use the flat amount. Verify: the fee is shown as a dollar figure or a precise percentage in the disclosure. Problem sign: the fee is buried in “points,” “processing,” or “administration” language without a clear cost.
-
Add the origination fee to the true cost of borrowing. For comparison, treat that fee as an additional upfront cost at time zero, and if the structure is unclear, confirm the treatment with a qualified professional and the loan disclosure. On a 36-month loan, an upfront fee has a bigger effect than on a 30-year mortgage, because you spread it over fewer payments. Verify: the fee is due at closing or deducted from proceeds. Problem sign: the lender says the fee is “financed” but does not show how that changes the amount you receive.
-
Find the late fee rule and the grace period. Check whether the lender allows 10, 15, or 30 days before a payment counts as late, and whether the fee is flat or a percentage. Verify: the contract names the grace period and the trigger date. Problem sign: the fee applies immediately after the due date or after a very short window that makes payment timing fragile.
-
Estimate how often a late fee could happen under real conditions. If your paycheck lands on the 5th and the due date is the 1st, a 4-day mismatch can matter. Verify: autopay, weekends, and holidays are handled the way the lender says they are. Problem sign: payments made on time from your bank still post late because of cutoff times or processing delays.
-
Read the prepayment section line by line. Look for whether the penalty applies to the first 2, 3, or 5 years, whether it is a percentage of the outstanding balance or several months of interest, and whether partial prepayments are allowed. Verify: the note specifies when the penalty starts and ends. Problem sign: the wording is vague, or the penalty applies even if you simply refinance.
-
Model your likely exit plan. Ask: will I keep this loan until maturity, refinance in 18 months, or pay it off early if I sell the asset? Verify: the penalty only matters if your plan includes early payoff. Problem sign: you cannot tell whether you will keep the loan long enough to make the penalty irrelevant.
-
Compare total cost under the same scenario. Add the origination fee, expected late fees, and any prepayment penalty that could apply to each loan. Verify: you are comparing the same repayment path on every offer. Problem sign: one loan is judged on “perfect payments” while another is judged on a refinance or sale scenario.
-
Rank the loans by the scenario that matters most to you. If you expect to keep the loan the full term, weight origination fees and late fees more heavily than prepayment penalties. If you expect to refinance or prepay, the penalty becomes central. Verify: the ranking still makes sense if you change one assumption, such as paying off 12 months early. Problem sign: the winner changes completely when the repayment plan changes by only a small amount.
That process sounds mechanical because it is. Fees are contractual, not emotional. I would not compare offers by headline rate alone unless every loan had the same fee structure, the same due dates, and the same payoff rules.
Which fee matters most depends on how you will use the loan
The fee that matters most is the one most likely to hit your actual plan. If you expect to carry the debt to maturity and never miss a payment, origination fees usually matter more than late fees or prepayment penalties. If you are stretched thin month to month, late fees can matter more than the rate because they pile stress on top of stress. If you expect to refinance, sell, or pay down early, prepayment penalties can dominate the comparison.
That trade-off is why a loan with a low rate and a 3% origination fee may not be the better deal for a short-term borrower. A fee paid upfront on a loan you keep for years becomes less painful over time. The same fee on a loan you refinance in 12 months is much more expensive in proportion to how long you kept the money.
Late fees deserve special attention because they often reveal how the lender handles operational friction. Some lenders give a 10-day grace period; others charge immediately after the due date or after a short cutoff time. The exact timing matters more than the dollar amount if your income is irregular or your bank transfers are slow. A $25 late fee can turn into a bigger headache than it looks if it repeats every month or if one late payment also triggers a credit reporting issue. Credit-reporting rules differ by country and lender, so read that section carefully.
Prepayment penalties are not always present, and when they are, the details matter. Some apply only in the first few years; some apply only to larger extra payments; some are designed to recover the lender’s expected interest income. A penalty tied to “the first 36 months” is very different from one tied to “any early payoff.” I’d treat a penalty as a serious warning sign if your plan is to refinance or sell within the penalty window. For background on mortgage closing terms and payoff rights, the CFPB and other consumer-protection agencies are useful references.
What should I check before I compare the offers?
Check the disclosure documents first, because fee language in an ad is not enough to compare real cost. The exact names vary by country and product, but the documents that matter are usually the loan estimate, truth-in-lending disclosure, promissory note, or credit agreement. In the United States, the Consumer Financial Protection Bureau explains the loan estimate and closing disclosure on its site; in the UK, the FCA’s consumer credit guidance and lender disclosures serve a similar purpose. The CFPB’s mortgage shopping tools and the FCA’s consumer credit resources are both worth reviewing alongside the contract.
Read the fee section with three questions in mind: Is the fee fixed or percentage-based? When exactly does it apply? Can it be avoided? Those questions usually separate a manageable fee from one that will surprise you. A 1% origination fee on a $50,000 loan is a different animal from a $300 flat fee. A late fee after 15 days is different from one after 1 day. A prepayment penalty that disappears after 24 months is different from one that lasts the full term.
I’d also check whether fees stack. Some contracts allow a late fee and an additional returned-payment fee if your debit fails. Others assess a prepayment penalty only on voluntary principal reduction above a certain threshold. If a contract uses terms like “all amounts due,” “accelerate,” or “default,” ask how those interact with the fee section before you sign.
A useful comparison sheet has at least these fields: loan amount, term, annual percentage rate or equivalent rate, origination fee, late fee amount, grace period, prepayment penalty formula, penalty window, and any waiver conditions. A simple one-page table is better than relying on memory. If the loan is large, the fine print deserves a slower read.
When should I stop and get qualified help?
Stop and get qualified help when the fee structure is tied to a refinance, a business loan, a mortgage, or any contract you do not fully understand. In those cases, the cost of a mistake can be larger than the cost of getting the paperwork reviewed.
The prepayment penalty is described with formula language you cannot follow: it may depend on yield maintenance, a step-down schedule, or months of interest — get a licensed adviser, loan officer, or attorney to translate the clause before you sign.
The loan is secured by your home, vehicle, or business asset: default can lead to foreclosure, repossession, or seizure depending on local law — have the contract reviewed if the fee terms are unclear and consult a qualified professional.
The late fee section is paired with default language or acceleration rights: one missed payment could make the entire balance due — ask a qualified professional to explain the trigger points.
The lender says the origination fee is “financed” but the amount funded is lower than the amount borrowed: your effective borrowing cost has changed — make sure you understand the net proceeds and whether the rate changed too.
You expect to refinance, sell, or make large extra payments within 12 to 36 months: the prepayment clause may matter more than the stated rate — check the actual payoff math before you commit.
The offer uses a variable rate with fee changes tied to index movement: the comparison can shift after closing — ask for a side-by-side estimate under higher and lower rate scenarios.
I’m not saying you need a professional for every consumer loan. I’m saying you should not improvise when the contract has moving parts, collateral, or terms that can trigger a large one-time cost. For a neutral consumer overview, the CFPB and comparable national regulators are good starting points.
The mistakes people make, and what those mistakes cost them
The biggest mistake is treating all fees as if they are the same kind of cost. They are not. Origination fees are front-loaded. Late fees are conditional. Prepayment penalties are scenario-based. If you lump them together, you can end up choosing the wrong loan for the way you actually use money.
-
Comparing rates without fees. The consequence is that the loan with the lower rate can be more expensive overall. Correct alternative: compare total cost including the upfront fee and any exit penalty.
-
Ignoring late fees because “I never pay late.” The consequence is that one bank holiday, payroll delay, or autopay failure can turn into repeated charges. Correct alternative: check the grace period, posting time, and whether weekends shift the due date.
-
Assuming prepayment penalties never matter. The consequence is paying extra when you refinance or sell. Correct alternative: read the payoff clause before signing, especially if you expect to move or refinance within 24 to 36 months.
-
Looking only at the amount, not the timing. A $500 origination fee on a 6-month loan hurts much more than the same fee on a 10-year loan. Correct alternative: spread the fee over the time you expect to keep the debt.
-
Forgetting partial prepayments. The consequence is that even extra principal payments can trigger a charge. Correct alternative: confirm whether the penalty applies to partial payments, not just full payoff.
-
Missing the lender’s posting rules. The consequence is a payment made on time by your calendar but late by the lender’s clock. Correct alternative: verify cutoff times, weekends, and electronic transfer posting rules, especially if you pay near the due date.
How do edge cases change the comparison?
Edge cases change the comparison by changing which fee is likely to hit first, or whether a fee is even allowed under the contract. A few examples matter a lot.
If the loan has a grace period of 10 to 15 days, a late fee may be less important than it looks, but only if you consistently pay inside that window. If the grace period is shorter or absent, late fees deserve much more weight.
If the origination fee is deducted from the loan proceeds rather than paid separately, you receive less cash than the note amount. That can distort comparisons if one lender quotes the fee upfront and another rolls it into the balance. Use the net amount you actually receive, not just the stated principal.
If the prepayment penalty is a percentage of the outstanding balance, it may shrink over time as you pay down principal. If it is based on several months of interest, it may be more sensitive to the rate than to the remaining balance. For that reason, the fee comparison can change if the contract changes from a balance-based formula to an interest-based one.
If a lender waives fees for hardship, autopay enrollment, or relationship pricing, the advertised comparison may not match what you actually pay. That is another reason to read the contract and not just the marketing page.